
Two disciplines that determine what a retirement looks like, and which are almost never planned together: how income is drawn, and how what remains is passed on.
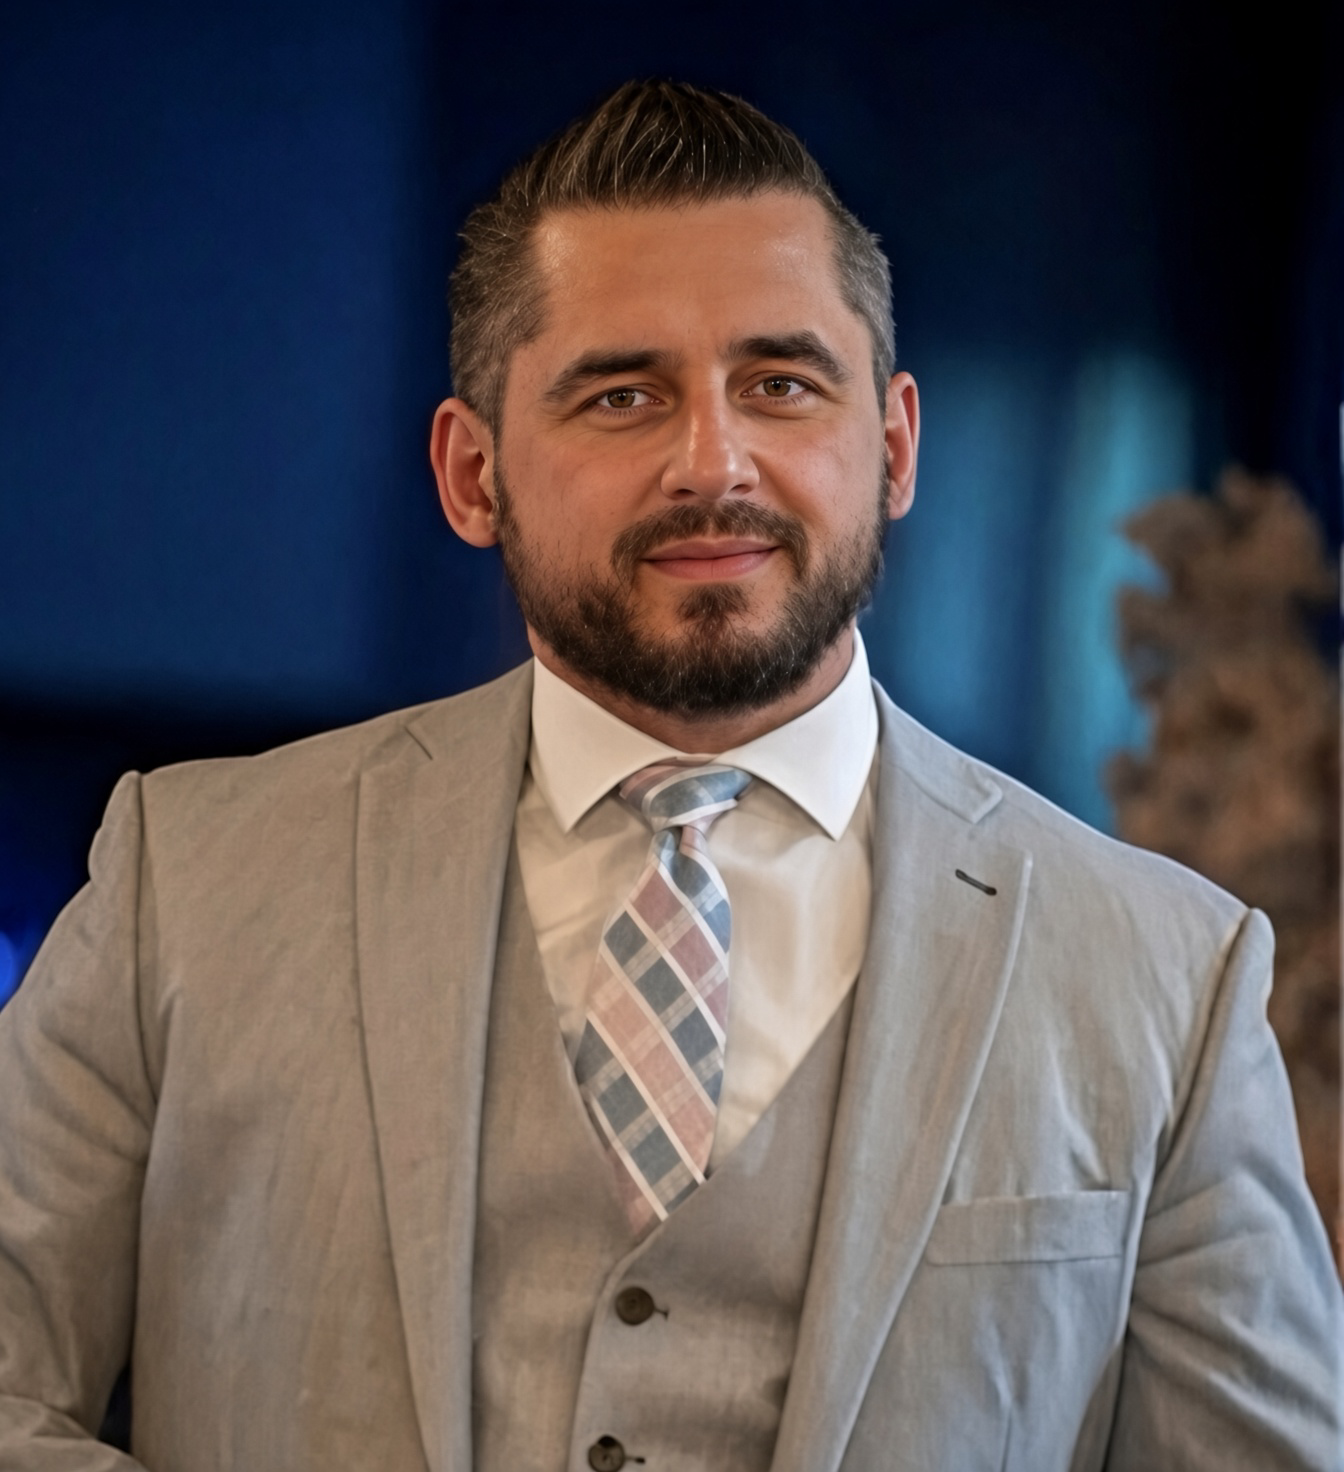
Gary Korolev, CFA, is joined by attorney Gerarda Culipher for a seminar covering both sides — the financial architecture of retirement income and the Virginia-specific legal structures that determine what happens to an estate afterwards.
Retirement & Estate Planning
Gary Korolev, CFAGerarda Culipher
The Financial Half
Five areas where the decisions are consequential, interconnected, and frequently made in the wrong order.
Social Security
Claiming strategy and the timing that fixes a benefit for life. Survivor and spousal provisions, and how a couple coordinates two filing dates to maximise household income rather than either individual's.
Medicare
Enrolment choices, and the gaps and penalties that follow from getting the timing wrong. Particular attention to federal retirees and to high-income households, where the rules bite differently.
Income Planning
Sequencing withdrawals across IRAs, 401(k)s, pensions, and annuities to minimise the lifetime tax bill — and adapting that sequence as inflation and markets move.
Federal Benefits
Guidance built for federal employees and retirees: FEHB, FERS, the Thrift Savings Plan, and the interactions between them that private-sector planning never has to address.
Long-Term Care
Protecting against three risks at once — sequence of returns, inflation, and health costs — through insurance and diversification rather than by hoping none of them arrive.
The Legal Half
Gerarda Culipher addresses estate planning as it works in Virginia specifically — where state law shapes the answers more than most people expect.
How do wills interact with probate court?
A will does not avoid probate — it instructs it. Understanding what that process involves, how long it takes, and what becomes public record is the starting point for every other decision.
How do trusts enable private probate?
Assets held in trust pass outside the public probate process. For families who would rather their affairs not become a matter of record, this is often the whole reason for the structure.
What changes when planning for decline rather than death?
Most estate documents address what happens after death. Cognitive or physical decline arrives first and requires a different set of instruments — the gap between the two is where families most often find themselves unprepared.
What financial benefits do trusts offer today?
Beyond privacy: control over timing and conditions of distribution, protection of assets for a surviving spouse, and coordination with the tax position of the estate as it stands under current law.
Why Both Halves, Together
Retirement planning has become more complicated, not less. New legislation, shifting markets, and continual change in healthcare all mean that a strategy assembled a decade ago is unlikely to still be the right one.
Social Security timing changes the tax position. The tax position changes the Medicare premium. Medicare and long-term care determine what the estate has left to pass on — and the legal structure determines who receives it, when, and whether privately. Decided separately, these choices work against one another. Decided together, they compound.
That connection is what the seminar is built around: tying Social Security optimisation, tax-aware income planning, the traps in Medicare, and the legal instruments of estate planning into a single strategy that holds for you and for the people who come after.
This seminar is educational and does not constitute financial, tax, or legal advice, nor a recommendation of any strategy or product. Estate planning is governed by state law and by individual circumstances; consult a qualified attorney in your jurisdiction. Rules covering Social Security, Medicare, and federal benefits change over time. Investing involves risk, including the possible loss of principal.
Bring Us Your Situation
A seminar covers the general case. Filing dates, withdrawal sequencing, and the right legal structure all depend on figures and family circumstances specific to one household. We're glad to work through yours.
BOOK A CALL →